Turkish Customs Passenger Commercial Goods Exemption Guide
Navigating passenger-accompanied commercial goods exemptions and thresholds under Turkish Customs Law.
Key Takeaways
- The statutory duty-free passenger gift exemption is capped at €430 for adults and €150 for minors under 15, applicable strictly to items lacking commercial character.
- Under Customs Law No. 4458 (Art. 235/3), undeclared non-commercial excess goods trigger an administrative surcharge of twice the assessed customs duties, whereas items deemed commercial lead to criminal prosecution under Anti-Smuggling Law No. 5607 (Art. 6/4).
- Customs authorities evaluate commercial quantity and nature based on objective criteria: repetition of identical models, factory packaging, the traveler's entry-exit frequency, and occupational profile.
- Selecting the Green Channel constitutes a legally binding declaration that no dutiable items are carried; travelers uncertain of their allowances should always choose the Red Channel to negate criminal smuggling intent.
- Administrative customs tax assessments and penalty decisions must be formally appealed within a strict statutory deadline of 15 calendar days pursuant to Article 242 of Law No. 4458.
Navigating Passenger-Accompanied Commercial Goods Exemptions and Threshold Disputes in Turkish Customs Law
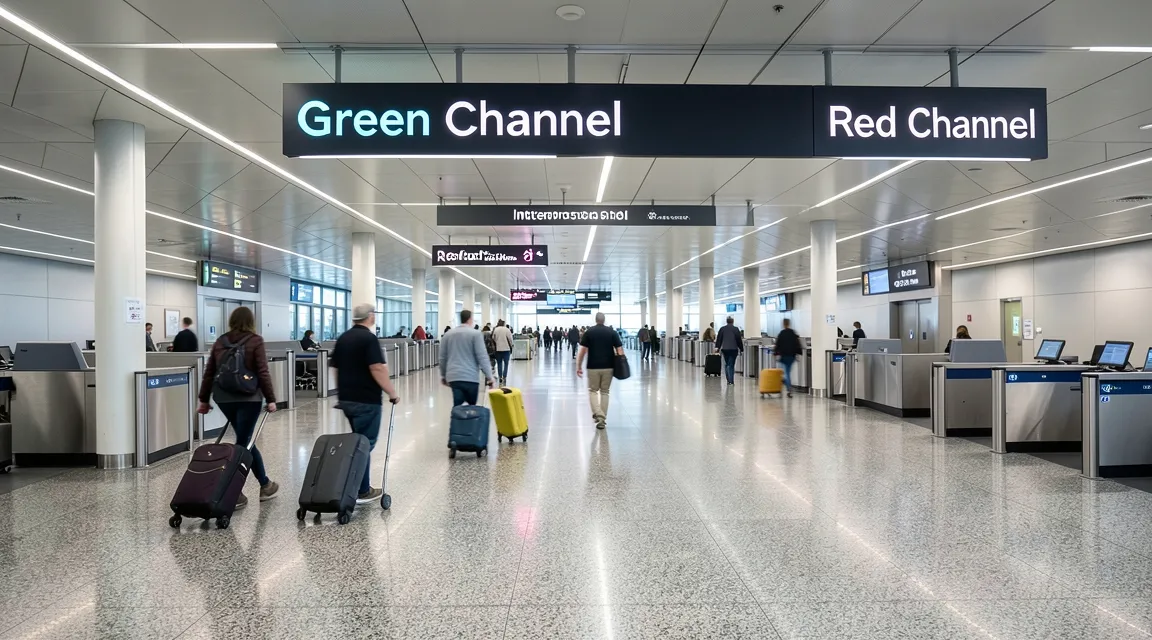
Stepping through the customs hall at an international airport or land border is often viewed as a routine procedural formality. However, beneath the green and red signage lies a complex, strictly monitored legal threshold. When a traveler carries items exceeding standard limits—or goods that border officials interpret as having a commercial character—a routine transit can swiftly transform into an administrative penalty or even a criminal investigation.
In Turkish border control practice, disputes involving passenger-accompanied commercial goods exemption (yolcu beraberi ticari eşya muafiyeti) and declaration thresholds represent one of the most contentious intersections of administrative customs enforcement and criminal defense. Whether the dispute involves electronics, high-value luxury items, or bulk personal purchases, the difference between an administrative duty surcharge and a formal indictment under Anti-Smuggling Law No. 5607 (5607 sayılı Kaçakçılıkla Mücadele Kanunu) hinges on statutory interpretation, quantity evaluation, and intent.
This comprehensive legal guide analyzes the statutory framework governing passenger exemptions, examines the criteria used to differentiate personal effects from commercial merchandise, and details procedural defense strategies for individuals confronting customs duty disputes or smuggling allegations.
1. Statutory Framework: Personal Effects, Gift Exemptions, and Tax Thresholds
Turkish customs regulations grant specific exemptions to travelers entering the Turkish Customs Territory, governed primarily by Customs Law No. 4458 (4458 sayılı Gümrük Kanunu) and the Council of Ministers Decision No. 2009/15481. Under Article 167/5-h of Law No. 4458, non-commercial personal items strictly intended for the passenger’s personal or family use are exempt from import customs duties.
Furthermore, Article 167/6-a establishes a statutory duty-free threshold for accompanied gift items:
- Standard Adult Allowance: Up to €430 in total intrinsic value per traveler (aged 15 and older).
- Minors’ Allowance: Up to €150 for travelers under 15 years of age.
- Personal Effects List (Annex 9 / Ek-9): Clothing, specific personal medical devices with prescriptions, limited electronic hardware (e.g., one personal mobile phone every three calendar years, subject to registration), and limited quantities of tobacco or spirits.
The Single Flat-Rate Duty (Tek ve Maktu Vergi) Regime
When a traveler brings goods exceeding the €430 threshold, but not surpassing €1,500, Turkish customs legislation allows for a simplified single flat-rate tax (yolcu eşyası gümrük vergisi), provided the items do not display a commercial quantity or nature:
- The statutory exemption of €430 is deducted from the verifiable value.
- The remaining excess value (up to €1,500) is taxed under single flat-rate percentages depending on the origin of the goods (e.g., standard preferential rates for goods originating directly from the European Union, higher standard flat rates for non-EU origins, with an additional 20% surcharge applied if the item falls under Special Consumption Tax Law No. 4760, List IV).
[PRO-TIP: Always retain original commercial invoices, fiscal receipts, and international payment confirmations. If a traveler cannot present proof of payment or if customs officials deem the declared value artificially deflated, customs authorities possess the statutory authority to establish an assessed value using comparative valuation databases, significantly raising duty bases and potential fines.]
2. The Legal Dilemma: Administrative Infraction vs. Criminal Smuggling
The central point of conflict in customs inspections is whether undeclared or under-declared goods constitute an administrative violation under Customs Law No. 4458 or a criminal smuggling offense under Anti-Smuggling Law No. 5607.
The transition from a regulatory irregularity to a criminal investigation is demarcated by two critical statutory provisions:
A. Article 235/3 of Customs Law No. 4458 (Administrative Penalty)
Under Article 235, paragraph 3 of Law No. 4458, if a passenger carries goods that fall outside the personal and gift exemption lists, fails to declare them, conceals them in personal baggage, or presents third-party goods as their own:
- The passenger is assessed the standard customs duties, plus an administrative penalty equal to twice the import duties (iki kat vergi cezası).
- Upon payment of this tax and fine, the goods are generally released to the owner—provided that the items do not bear commercial quantity and nature, and are not strictly prohibited or restricted imports.
B. Article 6/4 of Anti-Smuggling Law No. 5607 (Criminal Prosecution)
If customs authorities determine that the undeclared passenger-accompanied items possess a commercial quantity and nature (ticari miktar ve mahiyet), or if the items are prohibited imports, the administrative track is terminated immediately.
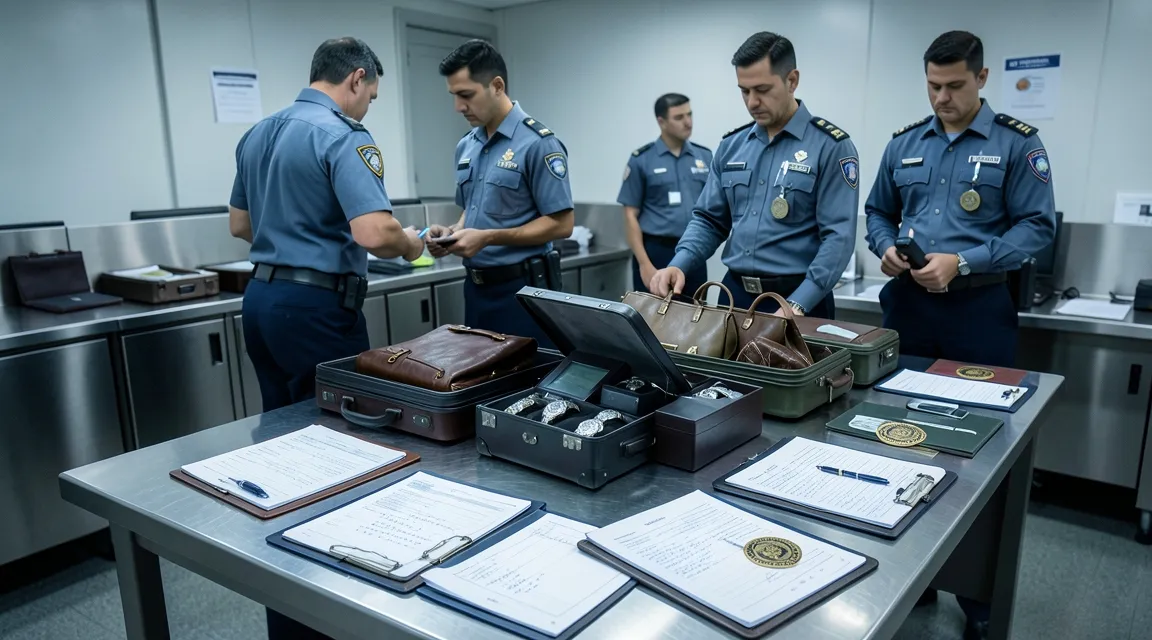
Pursuant to Article 6/4 of Law No. 5607, the incident is classified as criminal smuggling under Article 3. Customs enforcement officers seize the goods as physical evidence, prepare an official seizure report (Gümrük Muhafaza Zaptı), and transfer the file to the Chief Public Prosecutor’s Office (Cumhuriyet Başsavcılığı). The individual faces criminal prosecution carrying custodial sentences (imprisonment) and judicial fines, along with mandatory property confiscation (müsadere) under Article 13 of Law No. 5607 and Article 54 of the Turkish Penal Code (TCK).
3. How Customs Authorities Determine “Commercial Quantity and Nature”
In legal practice, the boundary between an innocent excess personal purchase and a commercial consignment (gümrük kaçakçılığı muafiyet sınırı) is rarely governed by a single statutory number. Instead, customs officials and criminal courts apply an evidentiary assessment based on subjective and objective factors:
                          EVALUATION OF PASSENGER GOODS
                                        │
           ┌────────────────────────────┴────────────────────────────┐
           ▼                                                         ▼
   PERSONAL / GIFT ITEM                                     COMMERCIAL NATURE
  • Diverse, single items                                   • Identical, duplicate models
  • Tags removed / unpackaged                               • Factory sealed / display packaging
  • Proportional to travel purpose                          • Bulk quantities beyond personal need
  • Infrequent international travel                         • High travel frequency / courier profile
           │                                                         │
           ▼                                                         ▼
   Customs Law Art. 235/3                                    Anti-Smuggling Law Art. 6/4
   (Administrative Double Tax)                                (Criminal Seizure & Prosecution)
Critical Factors Scrutinized by Border Enforcement:
- Homogeneity and Repetition: Carrying multiple units of the exact same item (e.g., five identical factory-sealed smartphones, dozens of designer handbags with tags, or complete sizing runs of luxury clothing) triggers an immediate presumption of commercial intent.
- Packaging and Condition: Items transported in original retail bulk packaging, sealed shipping boxes, or accompanied by commercial barcodes and wholesale display hangers are viewed as intended for resale.
- Travel Frequency and Itinerary: In our experience defending customs cases, border authorities routinely examine passport entry-exit records. Frequent same-day or short-interval trips to low-tax jurisdictions often lead inspectors to infer a systematic commercial courier activity (kurye faaliyeti).
- Professional Profile: Discrepancies between the passenger’s declared occupation, income level, and the volume or nature of the transported merchandise are frequently cited in enforcement reports to substantiate commercial intent.
4. Declaring Goods: The Legal Consequence of the Green vs. Red Channel
A widespread misconception among international travelers is that choosing the Green Channel (“Nothing to Declare” / Gümrüğe Tabi Eşyam Yoktur) is merely a passive exit route.
Under established customs jurisprudence:
- Walking into the Green Channel constitutes a legally binding tacit declaration that the passenger carries no goods exceeding statutory exemptions and no commercial inventory.
- If customs officers stop a passenger inside or immediately upon exiting the Green Channel and discover undeclared commercial items or goods exceeding the €430 threshold, the passenger cannot retroactively declare, “I intended to pay the tax.” The physical act of entering the Green Channel completes the administrative or criminal act of making a false declaration.
- Conversely, voluntarily entering the Red Channel (“Goods to Declare” / Gümrüğe Tabi Eşyam Vardır) and presenting the goods to officers precludes criminal smuggling intent under Law No. 5607. Even if the items cannot clear customs under passenger exemptions due to commercial volume, the passenger has complied with disclosure duties, channeling the dispute into administrative clearance, warehousing, or re-exportation procedures rather than criminal court.
[PRO-TIP: If there is any doubt regarding whether an item exceeds value thresholds or personal usage limits, always opt for the Red Channel. Voluntary disclosure eliminates the element of clandestine introduction (kaçak sokma kastı), shielding the passenger from criminal smuggling charges even if import duties or formal trade declarations are required.]
5. Procedural Remedies: Contesting Fines, Assessments, and Seizures
When a passenger encounters an adverse customs decision, procedural deadlines must be strictly observed to preserve statutory rights and avoid forfeiture of remedies.
A. Administrative Track: Customs Reassessment and Reconciliation
For disputes confined to administrative tax assessments and fines under Customs Law No. 4458 (such as contested classification, valuation, or tescilli eşya uyuşmazlıkları):
- Administrative Appeal (İdari İtiraz): Under Article 242 of Customs Law No. 4458, an affected party may submit a formal administrative objection to the competent Regional Directorate of Customs (Gümrük ve Dış Ticaret Bölge Müdürlüğü) within 15 days of notification of the assessment or penalty. Given the rigorous procedural thresholds and technical valuation methods applied during these administrative disputes, engaging experienced customs counsel ensures critical rights are preserved; Contact EG Law Firm for Professional Legal Assistance to formulate a tailored objection strategy.
- Reconciliation Procedure (Uzlaşma): As an alternative or parallel step under Article 244 of Law No. 4458, the taxpayer may apply for administrative reconciliation to negotiate reductions in disputed duties and fines.
- Tax Court Litigation (Vergi Mahkemesi): If the administrative objection is rejected, the taxpayer possesses the statutory right to file an annulment lawsuit before the competent Administrative/Tax Court within 30 days of the rejection notice.
B. Criminal Track: Defending Smuggling Allegations in Court
When border enforcement initiates proceedings under Article 6/4 of Law No. 5607:
- Preserving the Evidentiary Record: Counsel must immediately examine the seizure and incident report (Olay Yakalama ve Zapt Tutanağı). Discrepancies in counting, condition assessment, or passenger statements must be noted on the record.
- Challenging the “Commercial” Characterization: The defense must demonstrate subjective and objective proof of personal use. This involves presenting evidence of the defendant’s socio-economic standing, lifestyle, the intended non-commercial utility of the goods (e.g., wedding gifts, personal collections, specialized private medical needs), and absence of commercial resale infrastructure.
- Proving Lack of Intent (Kast Yokluğu): Criminal liability under Law No. 5607 requires general or specific criminal intent (dolus). Demonstrating legitimate confusion regarding customs signage, language barriers, or lack of concealment can be vital in persuading the court that no deliberate smuggling scheme existed.
- Repentance and Restitution Mechanisms (Etkin Pişmanlık): Under Article 5 of Law No. 5607, individuals facing smuggling charges may, in certain circumstances and within statutory procedural windows, benefit from significant statutory penalty reductions by paying double the custom tariff value of the seized goods to the state treasury before judgment is rendered.
Conclusion & Strategic Steps
Customs clearance is a formal legal process governed by strict statutory presumptions. Misunderstanding the boundary between personal gift allowances and commercial volume does not merely result in excess baggage fees; it can lead to severe financial penalties or criminal prosecution before the Criminal Courts of First Instance (Asliye Ceza Mahkemeleri).
If you are transporting high-value items, electronic hardware, or multiple units across international borders:
- Maintain Complete Documentation: Always carry authentic sales receipts, bank payment confirmations, and manufacturer certificates.
- When in Doubt, Use the Red Channel: Choosing the Red Channel remains the most reliable defense against criminal smuggling accusations.
- Act Quickly on Adverse Notices: Do not ignore administrative seizure or penalty protocols. Statutory timeframes for filing administrative objections under Article 242 (15 days) or challenging property confiscation are strictly applied by authorities.
- Seek Qualified Counsel: Consult an experienced customs and criminal defense attorney immediately upon the initiation of customs proceedings to safeguard your constitutional rights, preserve property interests, and navigate administrative or judicial litigation.
Legal Disclaimer: This publication provides general educational information regarding customs legislation and jurisprudence. It does not constitute formal legal advice, case-specific evaluation, or an attorney-client relationship. Individuals facing customs penalties or prosecution must seek customized counsel based on their specific evidentiary record.
Frequently Asked Questions (FAQ)
What is the monetary limit for duty-free passenger-accompanied gifts entering Turkey?
Under Article 167 of Customs Law No. 4458, the statutory duty-free exemption for passenger-accompanied gift items is €430 for travelers aged 15 and older, and €150 for travelers under 15 years old. This exemption is contingent upon the items not possessing commercial quantity or nature.
What happens if my accompanied goods exceed the €430 exemption limit?
If the total value of non-commercial goods exceeds €430 but does not exceed €1,500, a simplified single flat-rate customs duty (tek ve maktu vergi) is applied to the excess amount after deducting the €430 allowance. However, if the goods are deemed to be of a commercial quantity or nature, simplified passenger taxation cannot be applied, and standard import procedures or penalties are triggered.
When does carrying undeclared goods become a criminal smuggling offense?
Pursuant to Article 6/4 of Anti-Smuggling Law No. 5607, when undeclared passenger-accompanied goods are determined by customs officials to possess a commercial quantity and nature or are prohibited imports, the matter is classified as criminal smuggling. If the items are deemed non-commercial, the violation remains an administrative infraction under Article 235/3 of Customs Law No. 4458, punishable by customs duties plus a penalty equal to twice the duty amount.
Does choosing the Green Channel count as a formal legal declaration?
Yes. Under international customs conventions and Turkish customs jurisprudence, walking through the Green Channel constitutes an active, legally binding tacit declaration that you are carrying no goods subject to duties, prohibitions, or declaration thresholds. If commercial or excess goods are found in your luggage inside or exiting the Green Channel, you cannot avoid false-declaration liability by claiming an intent to declare later.
How can a traveler challenge an administrative penalty issued under Customs Law Article 235/3?
An administrative penalty must be contested within 15 days of formal notification by filing an administrative objection (idari itiraz) with the relevant Regional Directorate of Customs under Article 242 of Law No. 4458. The taxpayer may also apply for reconciliation (uzlaşma) under Article 244, or file an annulment lawsuit before the Tax Court (Vergi Mahkemesi) within 30 days if the administrative objection is rejected.